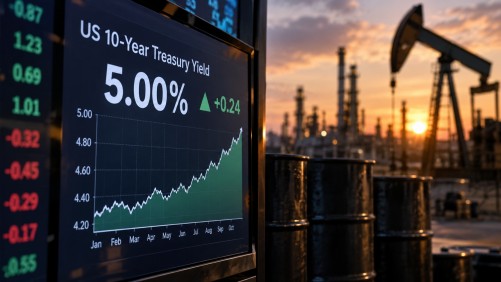
For the first time since 2023, the borrowing costs for the US government have escalated to 5%, as global bond markets experience a significant sell-off, fueled by climbing oil prices and mounting inflation concerns. The yield on the 10-year US Treasury bond reached this crucial 5% threshold on Monday, having previously dropped to about 4% earlier in the year. This upward trend has been ongoing since the US-Israeli conflict with Iran began in late February, marking the highest yield since October 2023.
This recent increase in bond yields coincides with Brent crude oil prices surging past $108 per barrel. The rise in oil prices follows a series of attacks on Saudi Arabian energy infrastructure and escalating tensions in the Middle East. Notably, drone strikes have caused Saudi Arabia to close a vital east-west crude pipeline, sparking fears of potential disruptions to global oil supplies. The situation is further aggravated by attacks linked to Iran-backed Houthi forces and escalating tensions near the Bab al-Mandab Strait.
Gulf states recently postponed talks with Tehran regarding a temporary shipping route through the Strait of Hormuz, a key global oil and gas supply route. This development has intensified concerns, particularly as higher energy prices add to inflationary pressures and create uncertainty around global interest rate trends. The financial community is keenly awaiting the US Federal Reserve’s impending interest-rate decision, with the Bank of England also expected to reveal its stance later this week.
The significance of the rise in US Treasury yields extends to the global financial landscape, as the 10-year Treasury is a critical benchmark for determining borrowing costs. Consequently, higher yields can escalate financing expenses for governments, businesses, and households worldwide. This trend is mirrored across Europe, where long-term UK government borrowing costs have soared to their highest in decades. The combination of rising energy prices and renewed geopolitical tensions has compounded fears that central banks may need to uphold tighter monetary policies for an extended period.
Throughout the year, oil prices have demonstrated considerable volatility. Brent crude initially increased from around $72 per barrel before the conflict, peaking at about $126 in April, then eased during the summer with hopes for a lasting ceasefire. However, as hostilities have intensified and diplomatic negotiations have faltered, prices have surged once more. With oil prices now exceeding $100 per barrel, markets are again facing concerns over inflation, interest rates, and the broader implications of prolonged disruptions to global energy and trade routes.